GST Council Approves Eight Reforms and Raises Prosecution Threshold
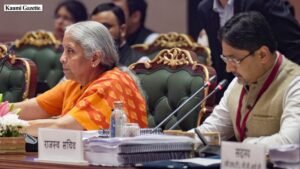
The 57th GST Council meeting concluded with the approval of eight key reforms aimed at streamlining registration, refunds, input tax credit (ITC), and enforcement, while keeping tax rates unchanged.
The GST Council stated that the tax rate structure is now settled and announced that future rate alterations will be handled once a year at a dedicated meeting. No alterations to tax rates were introduced during Thursday’s session.
Major enforcement adjustments include raising the prosecution threshold under GST from Rs 1 crore to Rs 5 crore, alongside the removal of the minimum punishment. Furthermore, the general penalty applicable where no specific penalty is prescribed will decrease from Rs 25,000 to Rs 10,000.
The government stated that these enforcement changes are possible because GST systems can now match invoices between sellers and buyers and identify fake credit closer to the source. Under the revised interstate transit rules, vehicles transporting goods across states can be stopped only on specific intelligence with prior authorization from an officer not below the rank of Joint Commissioner, restricted to inspections by source and destination states.
For small taxpayers, individuals with a turnover of up to Rs 5 crore supplying exclusively to consumers will be permitted to file an annual return while paying taxes on a quarterly basis. Out of 1.05 crore active taxpayers, roughly 16.85 lakh report exclusively consumer supplies, with nearly 99% falling below the Rs 5 crore threshold. Small sellers operating on e-commerce platforms can also designate an e-commerce operator’s warehouse in another state as their principal place of business with system consent, provided they maintain a physical presence in at least one state.
Registration procedures will see routine amendments—such as updates to trade names, directors, partners, or additional business addresses—accepted automatically. Data shows that between November 2025 and September 2026, 16.73 lakh applications sought registration amendments, with approximately 65.45% involving routine modifications.
Refund processes have been accelerated, reducing the deadline for acknowledging a refund claim from 15 days to 10 days, after which unacknowledged claims will automatically be treated as acknowledged. The system will sanction 90% of refund claims based on risk assessment, issuing orders within three working days of acknowledgement instead of the previous seven. Additionally, excess balances held in cash ledgers will be refunded fully automatically.
Tax paid on input services will become eligible for refunds under an inverted duty structure for credit availed beginning November 1, 2026, with plant and machinery tax refunds permitted from April 1, 2027. Input tax credit was also expanded to cover employee health and life insurance, telecommunication towers, pipelines located outside factories, free samples, and specific expired stock written off where destruction is mandated.
A Committee of Officers was established with a three-month deadline to examine protection frameworks for genuine buyers possessing proper invoices who received goods and paid suppliers in full. The panel’s findings will return to the GST Council for review.
Related stories
More from Explainers
 ExplainerHow black holes become cosmic monsters: Scientists uncover the violent merger chain behind giant space objects |
 ExplainerWhy the ‘Trump rally’ is hitting a wall of profit-takingExplainerWhy India’s defence sector boost drone output for next-gen combat
 ExplainerHow David Attenborough’s lush imagery hid a history of colonial harm
 ExplainerWest Bengal (WBBSE) Madhyamik Result 2026 LIVE: Class 10 scorecard today at wbbsedata.com — How to check at 10:15 am
 ExplainerCBSE 12th Result 2026: How students can access scores via DigiLocker, UMANG and SMS